News
IFA reveals its new chief executive
Wednesday 2nd of June 2010
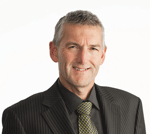
Lee is currently national marketing manager at Fidelity Life and his new appointment is effective from early July.
The former chief executive David Hutton stepped down in December after three years at the association's helm.
IFA chairman Phillip Meyer says the Institute is fortunate to have attracted a candidate of Lee's calibre.
Want to read the full article?
Click the button below to subscribe and will have free unlimited access for a limited time to full article and all other articles on the site.
You will also be able to comment on articles on Good Returns.
Latest News
Latest Comments
Fund manager CEOs want KiwiSaver access lowered to 60 — with a catch
Yes agree with access to kiwisaver at age 60, raising super age to 67 or 68, and if we going to down the Australian path, asset test the pension also
5 days ago Lynda Edwardson
FMA outlines its latest expectations for advisers
@JP Well a lot complained about doing a basic Level 5 paper. Then, you confirm my statement when you explain about educating the public. I guess in short, if you want cut through, we need to use less than 6, six letter words, sad but true. This would likely require a thematic.
6 days ago Backstage
FMA outlines its latest expectations for advisers
I sincerely hope the adviser community can handle more than six six-letter words in a sentence. If you can’t, please hand in your license.
The average policy wording is way harder than that!
Passively-Aggressive, well said. When you only have a hammer, everything is a nail… scope creep with adviser expectations is a core part of the issue.
The recent messaging from the regulator seems to be being translated to: advisers have to provide the public education for the decisions that clients make in the future without a financial adviser because that’s where the actual harm is. Completely ignoring that at least 40% of the population is not engaged with the advice community. More if you exclude VIO’s as educators because they don’t.
It’s almost a case of needing financial literacy to be taught within the schooling system? Interesting concept!
It’s been said elsewhere that basic skills to “adult” are needed from schooling, because relying on it from parents that are financially (and other skills) illiterate isn’t working…
But we couldn’t possibly do that, it would make the system exploiting the masses much harder…
1 week ago Jon-Paul Hale
FMA outlines its latest expectations for advisers
I agree with the "prevalence-induced" concept. It is definitely not Advisers re-defining what we're seeing or over-reacting to the "maturing" of regulation.
The concept Steve put forward suggests that as the problem becomes less frequent, the criteria used to define the problem expands, resulting in lesser problems being treated like greater problems.
The root of the regulations we have is based in answering questions nobody asked, addressing problems Advisers did not cause. Such as blaming investment advisers for the losses direct investors took from finance company collapses, or allowing lobbyists to succeed in defining BEOT VIOs' sales processes as "advice".
So from the beginning - 2011 onwards - there has been so little prevalence of problematic advisers causing terrible outcomes through faulty advice processes that it does appear that the regulators are defining lesser problems as greater.
Paul – the “rules” are not rules. Everyone knows what a forward pass is, and we all know that a whiskey still counts as a stroke. Our regulations are mostly principles supported by vague guidance notes. You have correctly pointed out that there has been a lighter touch at times, and perhaps a sledgehammer at other times. To a FAP owner that looks like inconsistency. With no clear safe zone, just vague principles to abide by, and watching patchy and inconsistent enforcement, FAPs have taken an approach to documentation and processes that are now being criticised by the same people who won’t set a bar. But they will say we’re jumping too dam high. “Size it right” is an insulting suggestion from someone who won’t say what the right size is.
Recall people like Brent Sheather and Murray Weatherston openly and rightfully questioning what on earth was the problem these regulators and regulations were meant to solve? Recall also their criticism of the revolving door between the regulator and the regulated.
If it feels like they are moving the goal posts it’s because they are starting to approach molehills with climbing gear.
The hills are the same size. And they were never that big.
1 week ago agressively passive
FMA outlines its latest expectations for advisers
Paul Flood: The danger is that the 'goalposts' (regarding what is acceptable or unacceptable adviser conduct) may be susceptible to change. Our 'Principles based' legal/regulatory environment lends itself to “prevalence-induced concept change” over time, perhaps not so much in the written laws and Code, as in the interpretation of the prescribed principles.
2 weeks ago Steve Wright