

Is protecting retirement provision a life adviser’s duty? Part One
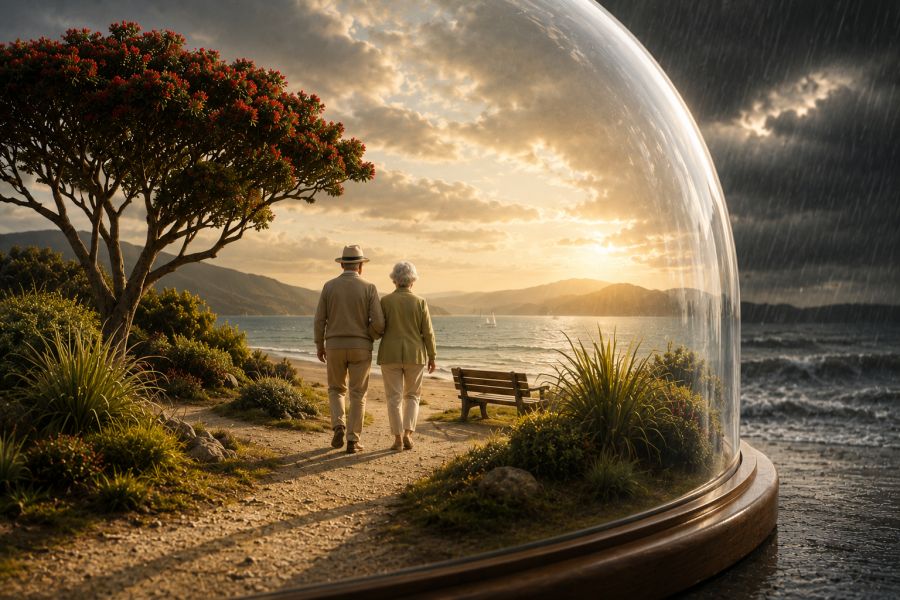
Is this a risk that life advisers (including those who are not qualified to give advice on wealth creation/retirement provision) must nevertheless consider?
I believe it is. Death, disability and poor health is a risk to retirement funding and if that’s not the domain of the life adviser, then whose is it? Why should life advisers stop protecting a client’s ability to pay the bills at age 65 or 70?
I’m not saying life advisers should be engaging in retirement planning or plan creation or commenting on the adequacy of KiwiSaver balances or contributions (unless they are competent to do so of course).
What I am saying is that life advisers should consider the negative impact of death, disease and disability on their client’s ability to retire (and that of their spouse/partner) and how they might mitigate that risk by their insurance recommendations.
Click the button below to subscribe and will have free unlimited access for a limited time to full article and all other articles on the site.
You will also be able to comment on articles on Good Returns.