

ANZ mortgage adviser lending plateaus
Mortgage advisers share of home loans written at ANZ, in the past year, sits at 61%, unchanged from a year ago.
While the flow of new loans remains unchanged, the overall propotion of ANZ's home loan book writtten by advisers increased slighltly from 53% to 54%. Two years ago it was 52%.
The figures come as ANZ's home loan book grew from $116 billion to $121 billion in hte 12 months ended September 30, while its share of the New Zealand mortgage market fell from 30% to 29.7%.
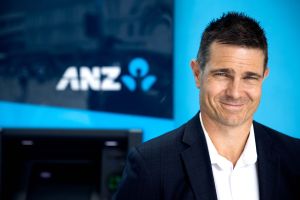
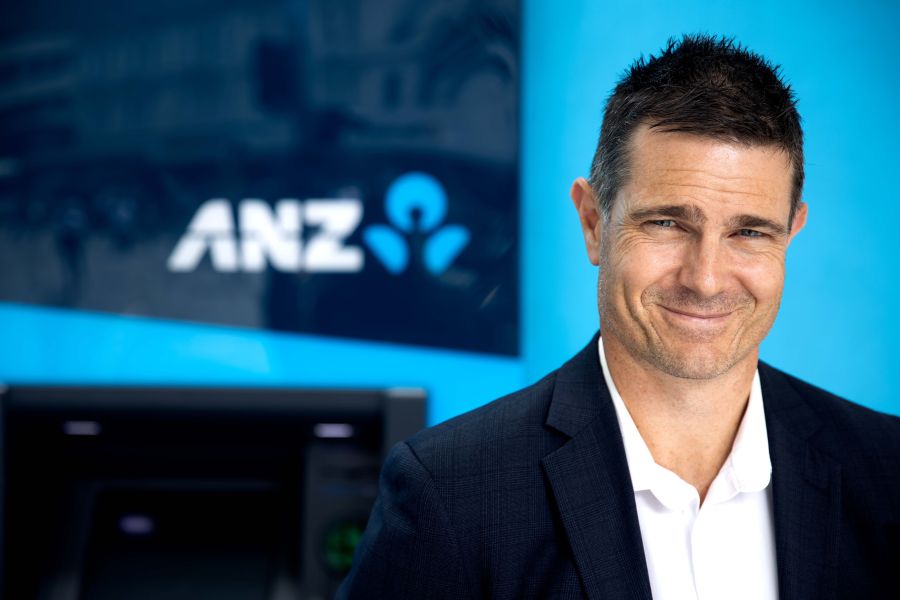
ANZ chief executive Ben Kelleher says the bank remains committed to both distribution channels.
"We're really focused on being the best we can for customers that choose to go through a mortgage adviser, and the best we can for customers that choose to come to us directly."
Kelleher says it is difficult to predict if advisers' share of business has plateaued.
"I think it's really customers' choice," he says.
The bank's investor figures show new home lending increased from $26 billion to $29 billion during the year, while the number of mortgage accounts rose from 572,000 to 602,000.
The average size of new loans increased from $416,000 to $431,000.
Kelleher describes the mortgage market as highly competitive, with switching activity having roughly doubled over the past five years.
"We fight every day to try and win home loan customer favour, and we're very focused on doing that across the mortgage adviser market as well as our own internal proprietary teams."
He says the bank continues to receive positive feedback from advisers about its mortgage turnaround times, although he did not disclose turnaround times like Westpac did last week.
Asked whether processing times could deteriorate when lending volumes recover, Kelleher acknowledges that sudden increases in demand can put pressure on banks.
"When things do pick up, sometimes it can take a time to adjust to that."
However, he says ANZ is investing in technology to improve processing efficiency and maintain service standards.
AI and mortgage fraud
ANZ is looking to use artificial intelligence to identify mortgage fraud that may be difficult for people to detect.
Kelleher says the bank has used AI and machine learning in parts of its business for several years, although their use in assessing mortgage applications remains limited.
He identifies three priorities for AI: improving customer experiences, increasing productivity and strengthening risk management.
On mortgage fraud, he says ANZ has encountered cases over time and is exploring how AI can help identify suspicious activity earlier.
"We have seen various instances over time of mortgage fraud in the market," he says.
The bank wants to use AI to identify things that are not as easy for a person to pick up.
However, Kelleher does not agree with suggestions that mortgage fraud has become a major problem for ANZ.
"I wouldn't say it's a big issue," he says, while stressing that the bank takes fraud seriously and works with regulators and the industry to prevent it.
ANZ's wider fraud and scam prevention efforts have produced improved results.
The bank says reported fraud and scam cases fell 5% during the year, while customer losses declined 37%. Nine out of 10 reported cases resulted in no customer loss.
Kelleher says AI offers opportunities but also introduces risks that require strong oversight and controls.
Profit falls as lending grows
ANZ New Zealand reported a statutory net profit of $2.359 billion for the year to September 30, down 7% from $2.532 billion.
Cash profit fell 3% to $2.306 billion.
Revenue increased 3% to $5.302 billion, but operating expenses rose 9% to $1.982 billion, including a provision relating to the Credit Contracts and Consumer Finance Act class action.
Excluding that provision, expenses increased 3% and cash profit rose 1%.
Net interest income increased 3% to $4.586 billion, although the bank's net interest margin fell seven basis points to 2.52%, reflecting competition in the lending market.
Credit impairment charges were $42 million, compared with a $25 million release the previous year.
Overall lending increased 3%, while customer deposits grew 4%.
Home lending rose 4.4%, despite a subdued housing market, and business lending to smaller customers increased 9.1%.
Kelleher says the economic recovery remains uneven, with agriculture and tourism performing better than some household-facing sectors.
ANZ expects house prices to fall around 2% in 2026, followed by a broadly flat market in 2027.
The bank also helped more than 10,700 first-home buyers purchase properties during the year, a 7% increase.