

Advisers embrace Westpac after trail commissions removed
Westpac is seeing some of its biggest ever flows from mortgage advisers despite the bank removing trail commissions earlier this year.
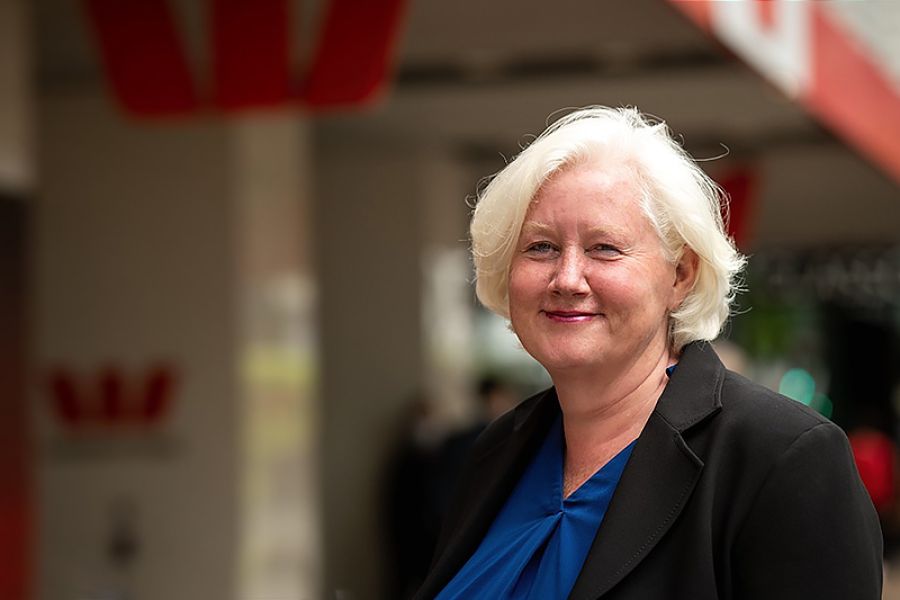
Westpac chief executive Catherine McGrath said flows from advisers stood at 70% of all mortgages written in the 12 months to September 30.
Overall, the portion of Westpac’s total home loan book written by advisers has risen from 59.5% a year ago to 62.3% this year.
The bank reported today that its annual profit for the year dropped 14% one the back of a declining net interest margin and expenses and loan impairment charges rising.
McGrath described the result as “pretty solid”.
She says competition for home loans is fierce at the moment. As an example one in every four loans written in August was a switch from another lender.
Also there has been a change in customer behaviour, where if the bank had customers on variable rate, they might have moved on to the fixed rate if they thought the market had bottomed. Likewise, Westpac had seen increased usage of its offset product.
She said there had been strong pricing competition for home loans and borrowers were shopping around.
“Customers (are) just really having the confidence to shop around, and it’s easy to switch. So they are definitely making the most of a competitive market.”
The bank touted that home loan turnaround times had gone from eight-plus days to one day. McGrath said “we’ve invested well in the broker origination channel, and we’ve been using AI tools in particular to make sure that the submissions we get are in great shape.”
As TMM reported recently, one adviser suggested turnaround times had improved as volumes are down. When the market picks up they will balloon out again as banks won’t have re-resourced their broker units.
McGrath had no comment to that suggestion.
Westpac recorded 4% annual home loan growth, to $74.5 billion for the year. This was below the overall market growth of 5.4%.
Its net profit after tax dropped $167 million, or 14%, from the previous year to to $1.036 billion.
Net operating income fell $128 million to $2.991 billion, as operating expenses rose $27 million to $1.520 billion with ongoing technology investment. Meanwhile, annual loan impairment charges were $33 million swinging from benefits, or write-backs, of $44 million the previous year.