

Investments
Market Review: Can the good times roll for yet another year?
Tuesday 5th of December 2006
|
This market summary is provided by Tyndall Investment Management. To see how the numbers stacked up for various markets around the world in the past month and over the year, visit our Monthly Market Review here |
As the year draws to a close it is time to reflect on the performance of the various markets through 2006 and to preview next year. The year to date index performance figures (before tax and fees) for the key investment sectors that we invest in (and for the three previous calendar years) are shown in the table below.
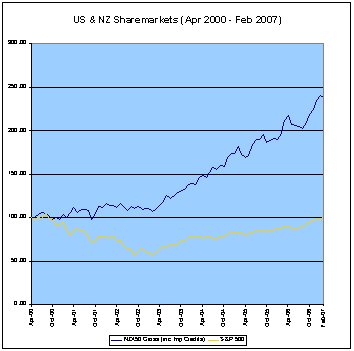
Some key global themes for next year are:
- Global growth slowdown (but off a high base). Economic growth rates are expected to fall slightly in all the major economies (Europe, Japan, China and the US) in 2007. However, global economy activity is expected to still be robust and well balanced.
- China. China is trying to slow its economy as it grapples with various growing pains. However, its GDP is still expected to be up almost 10% in 2007 - that’s a slow down!? Thus, it is expected to still be a significant positive influence on the global economy next year.
- Slowing corporate earnings growth. Like the global economy, corporate growth rates are expected to ease in 2007, but off very high levels. For example, for the September quarter in the US the result was a 19% growth out-turn! To date the earnings risk has been on the upside, which has helped keep US sharemarket P/E multiples respectably in the mid-teens. However, the risks may now be moving to the downside with single digit earnings rather than double digit growth likely to be the norm in 2007.
- Inflation looking under control. Central bankers have been paranoid about second round impacts from oil prices. However, this doesn’t seem to have happened with productivity gains in the US continuing and export goods from Asia to the rest of the world remaining a deflationary force. Falling oil prices have helped further and inflation forecasts for all the major regions for 2007 are below 3% - hardly suggesting a resurgence in global inflation.
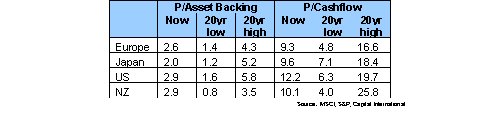
- Market valuations not overly stretched. As shown below, even with the healthy gains in global sharemarkets strong earnings growth has helped keep market valuations well below over priced levels. Price to cashflow multiples for the major markets are all in the middle of their 20-year ranges. The key will be whether earnings get crunched in 2007, thus lifting valuations to upper quartile levels. At this stage that seems unlikely.
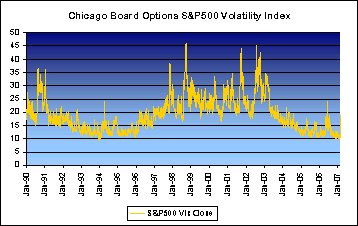
- A slump in commodities prices
- The US housing collapse deepening
- Global imbalances finally leading to big shifts in interest rates and currencies (e.g. USD weakness)
- Over-zealous central bankers over-tightening monetary conditions
- Oil price going through the roof
- A one-off shock (SARS, Iran, Iraq, North Korea, terrorist attacks).
Ph: (09) 377 7262 or 0274 895 568
Email:anthony_quirk@tyndall.co.nz To see how the numbers stacked up for various markets around the world in the past month and over the year, visit our
Anthony Quirk is the managing director of Tyndall Investment Management New Zealand Limited (Tyndall).
Want to read the full article?
Click the button below to subscribe and will have free unlimited access for a limited time to full article and all other articles on the site.
You will also be able to comment on articles on Good Returns.
Latest News

4 min read


3 min read

3 min read



