

NZ & Australia Company Results Review
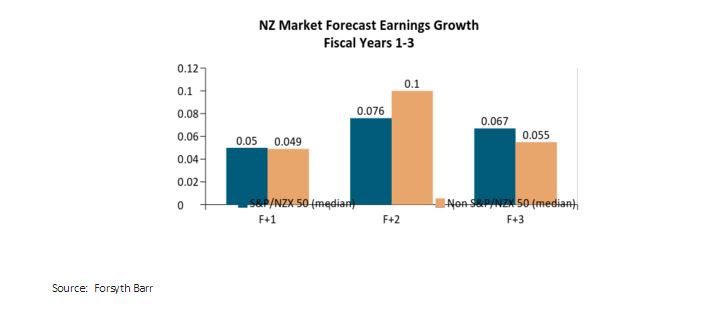
Company outlook statements were cautious, with signs of a broad softening in activity levels. Both Diligent (+19.4% over February) and Nuplex (+21.5%) received takeover offers during the month, underpinning the valuation of the New Zealand equity market.
The Australian reporting season was better than expected, with more companies beating market expectations than missing them. Resource companies outperformed as commodity prices stabilised (particularly iron ore and gold) and low earnings expectations were met or exceeded.
Locally it was the best since 2012 with fewer downgrades and more upgrades. Across the Tasman results were better than feared with earnings revisions lacking their normal downward bias.
Share price weakness going into the results season has mostly been attributed to global concerns rather than specific influences from Australia or NZ. Weakness in global banks saw Australian financial stocks selloff significantly in sympathy, rather than reflecting actual results or underlying bank sector influences (see Bank section below).
Most pleasing individual result?
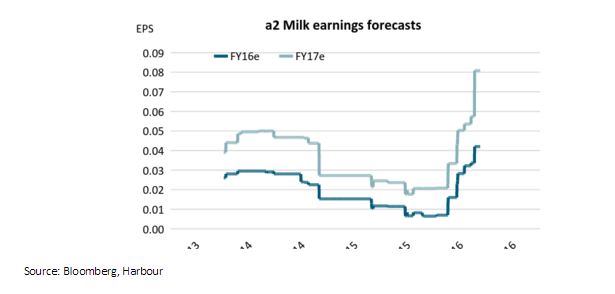
a2 Milk presented its full year result during the month delivering sales and earnings well ahead of consensus expectations. However, it was the upgraded guidance for FY16 that caught the markets attention. This was the third earnings upgrade by the company in as many months, with infant formula sales being the key driver of the upgrade. The result suggests strong demand for infant formula in China, highlighting that the company has been successful at building a brand that consumers trust and want to buy. The a2 stock price, however, did not respond to the improved outlook on an expectation that the regulatory environment in China will make it harder for companies such as a2 Milk, Bellamy’s and Blackmores to distribute product to China via so-called grey channels. The a2 Milk Company has significantly increased sales through official distribution channels and signalled that this trend will continue, reducing the potential for adverse regulatory impacts.
After years of looking expensive, the a2 stock price is no longer a valuation outlier. The a2 stock price is currently trading at 22x forecast FY17 Price-to-Earnings multiple, which places it 11th in the ranking of New Zealand stocks on a price-to-earnings multiple. This suggests that the market is demanding a significant risk-premium for the potential regulatory risks and possible general execution risk into new jurisdictions.
Click the button below to subscribe and will have free unlimited access for a limited time to full article and all other articles on the site.
You will also be able to comment on articles on Good Returns.