

NZX 50 falls as blue chips F&P Healthcare, Meridian chilled in global slide
New Zealand’s S&P/NZX 50 index fell as heavyweights Fisher & Paykel Healthcare, Meridian Energy and Infratil were among the bigger drags on the local board following Wall Street’s slump on Friday.
Stocks across Asia were mixed, with Chinese markets buoyed by speculation that financial regulators would meet banks and trading firms to support the capital market, while Australian stocks fell ahead of the Reserve Bank of Australia’s expected rate hike on Tuesday and as Westpac Banking Corp’s annual earnings showed margins in the mortgage market.
KMD Brands jumped to its highest level since June after the retailer’s board entered exclusive talks with a potential suitor, while Warehouse Group advanced on ambitious plans to grow its earnings.
And Locate Technologies was unchanged after the Bitcoin treasury company liquidated its holdings of crypto assets amid growing security risks from AI and quantum computing.
Cool winds
The NZX 50 dropped 98.37 points, or 0.7% to 13,698.63, with 30 stocks declining, 17 gaining, and three unchanged. The S&P/NZX 20 index futures contract for December dropped 1.1% to 7,470, with 50 lots traded for a value of $374,000, while the NZX 20 slipped 0.5% to 7,504.14.
Turnover across the main board was $127.1 million, of which F&P Healthcare accounted for $42.1 million, with the country’s biggest listed company sinking 3.2% to $46.13.
Among other heavyweights dragging on the index, Meridian fell 2.2% to $5.40 and Infratil declined 0.6% to $12.44.
“We saw a bit of a selloff in the tech stocks in Friday’s session and that’s flowed through to our market,” said Jeremy Sullivan, an investment adviser at Craigs Investment Partners. “Fisher & Paykel Healthcare makes up 20% of our bourse, so when you get a relatively large move from them it’s a considerable weight on our index.”
Stocks across Asia were mixed, with New Zealand’s market joining declines for Australia’s S&P/ASX 200 index and Singapore’s Straits Times Index, down 0.6% and 1.4% respectively in late trading.
Meanwhile, Chinese markets rallied on reports that financial regulators would meet bankers and securities firms to discuss ways to support capital markets, with Hong Kong’s Hang Seng up 0.6% and the Shanghai Composite advancing 1.2%.
And tech-heavy markets in South Korea and Japan also recovered, with the Kospi up 2.6% and the Nikkei 225 index gaining 0.4%, as US futures pointed to a positive start to the week for Wall Street.
Craigs’ Sullivan said there was a long list of things to occupy investors this week, including the US midterm elections, central bank meetings in the UK and Australia, US manufacturing and service activity data and employment figures, along with corporate earnings season.
Across the Tasman, banking stocks were weaker as National Australia Bank and Commonwealth Bank of Australia cut their economic growth outlooks ahead of the RBA policy review on Tuesday, which is expected to deliver a quarter-point hike to 4.85%. The kiwi dollar traded at 79.97 Australian cents at 5pm in Auckland from 80.12 cents on Friday, and fell to 56.17 US cents from 56.41 cents last week.
Big red
Dual-listed Westpac declined 1.1% to $45.50 on the NZX after reporting a 1% decline in annual profit, with margins squeezed amid a tight mortgage market in Australia. Its New Zealand arm reported a 9% slide in annual profit, with increased provisioning for bad debts weighing on the bottom line.
ANZ Group Holdings, which reports next week, increased 0.4% to $50.50.
Stock market operator NZX posted the steepest decline on the NZX 50, falling 4% to $1.46, while Briscoe Group dropped 2.8% to $4.11.
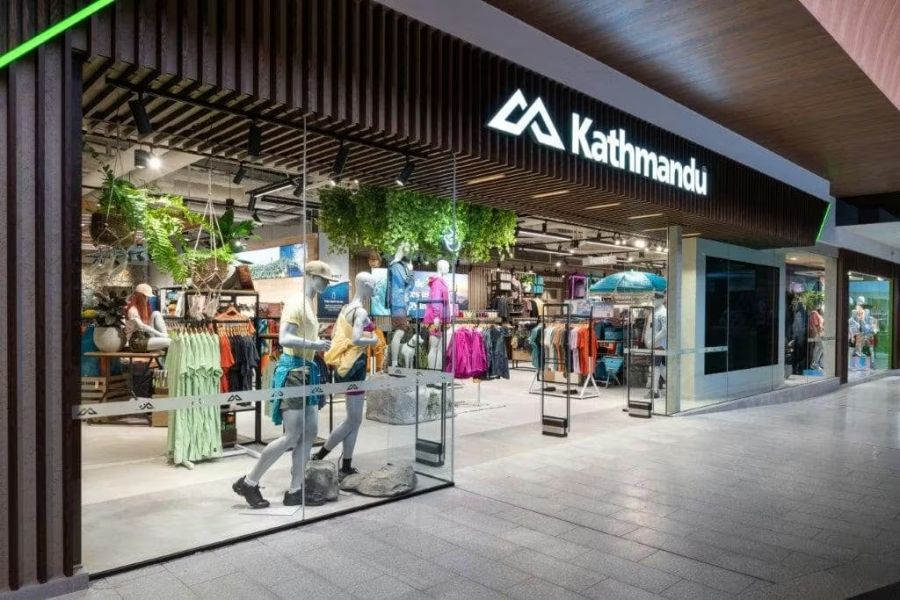
KMD Brands jumped 12% to $2.09 after the retailer said it provided US consumer brand group Bluestar Alliance exclusive due diligence access, having shopped itself around after attracting unsolicited bids.
Among other companies to gain, Ebos Group rose 3.9% to $21.29 after The Australian newspaper’s DataRoom continued to speculate that the healthcare products group was being shopped to private equity firms, despite chair Liz Coutts telling shareholders last month that there hadn’t been any takeover approaches.
Tourism and transport firms were stronger as Brent crude oil futures fell 3.1% to US$109.94 a barrel at 5pm. Auckland International Airport rose 1.8% to $8.58, Air New Zealand increased 1.3% to 38 cents and Tourism Holdings advanced 1.1% to $2.83.
Outside the benchmark index, Warehouse climbed 3% to 68 cents after the big-box retailer said it was targeting $100 million of operating profit within three-to-five years, more than four times the $22.6 million it reported in the 2026 financial year.
“Getting to $100 million of operating profit in three-to-five years is certainly ambitious,” Craigs’ Sullivan said.
Locate Technologies was unchanged at 4 cents after the software firm and Bitcoin treasury group sold its $1.7 million holdings of Bitcoin to reduce the security risk crypto assets faced from AI and quantum computing. No decision had been made on how to use the cash, and the board was still open to holding Bitcoin in the future.
Bitcoin rose 0.8% to US$78,381 as it continued to claw back some of last week’s losses after the Binance hack and theft of US$6.3 billion of crypto assets, some 95% of which has been covered by the exchange.
The Smart Bitcoin exchange-traded fund rose 0.8% to $2.99.
Reporting by Paul McBeth.